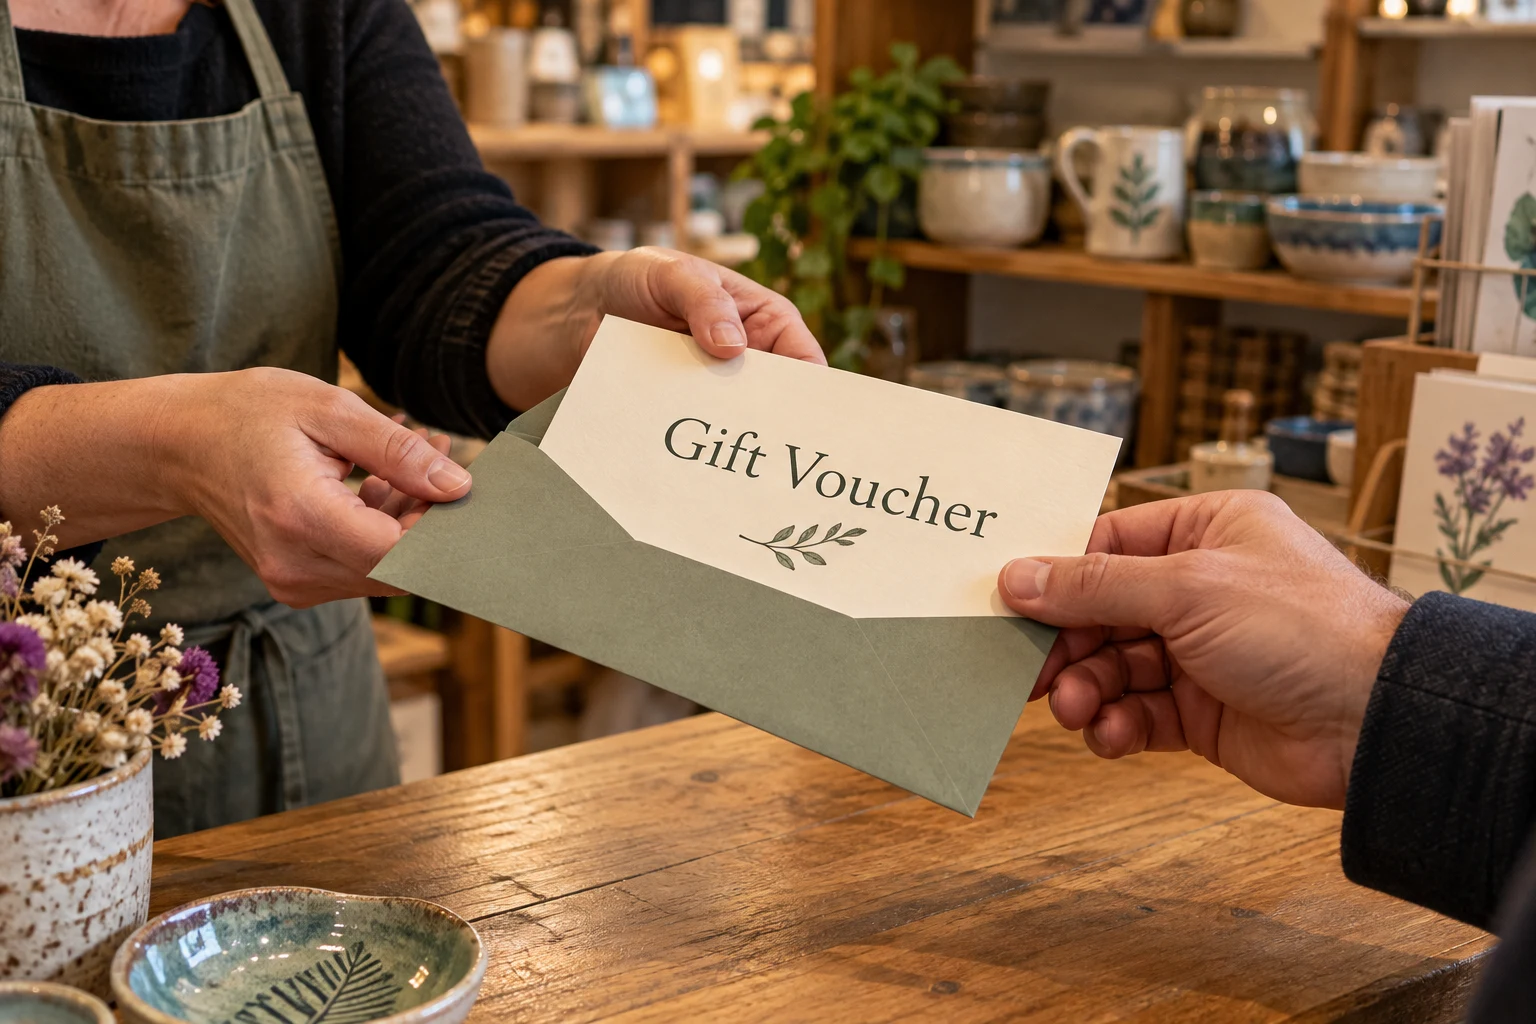
“Gift card” is a description on the front of a product, not a complete explanation of the rules behind it. A voucher for one shop and a prepaid payment card may look similar in an envelope but have different protections.
Before buying a voucher for someone else, record who issues it, where it can be spent and which terms apply. That small amount of research is more useful than assuming every card sold in Ireland has identical expiry and replacement rules.
Sort the product into the right group
The CCPC’s consumer voucher guidance explains that covered shop or chain vouchers and certain shopping-centre cards must be valid for at least five years. Some can have no expiry date. Electronic-money cards, loyalty rewards, credit notes and certain short-dated deal vouchers are excluded from those particular rules.
A branded card accepted across unrelated retailers should therefore prompt a check of its actual issuer and product type. Exclusion from the gift-voucher Act does not mean that every other consumer protection disappears; it means the five-year rule cannot simply be applied by analogy.
Check partial spending and the written record
The CCPC’s business requirements for vouchers set out the obligations on covered issuers. The expiry information should be supplied in writing. Consumers cannot be required to spend the full amount at once or prevented from combining vouchers for one purchase. Where a balance greater than €1 remains, it must be dealt with through the permitted refund or replacement-voucher arrangements.
Keep the written terms with the original purchase evidence. A photograph of the front of a card may not show the issuer, purchase date or conditions. If a replacement voucher is provided for a remainder, check its expiry against the original rather than treating the replacement date as a fresh purchase.
An original voucher ledger
A household or small organisation giving several vouchers can use a simple ledger with six fields: issuer; recipient’s own reference; amount bought; purchase date; written expiry or no-expiry confirmation; and balance after each use. Keep any security code separately from a shared list.
For example, a hypothetical €60 covered voucher used for a €42 purchase leaves €18. The useful record is the original €60 purchase, the €42 spend and how the €18 was preserved. Do not mark the whole voucher “used” merely because it has been presented once.
This example is arithmetic, not a statement about an actual retailer’s policy. The method also makes it easier to reconcile two vouchers used together without losing track of the remaining value.
Five years is not a business-survival guarantee
The statutory minimum does not insure a retailer against closure. Nor does it mean an anonymous lost voucher must always be replaced. Consider the practical risk of leaving a large balance unused, and retain proof of payment.
If a problem arises, distinguish whether the voucher itself failed, the goods or service bought with it were faulty, or the issuer ceased trading. Those are different complaints. Start with the relevant business and written evidence rather than assuming that an expiry date alone resolves all three.
Join the conversation
Keep it kind, relevant and constructive. Comments are reviewed before they appear.
Be the first to share a thought.